
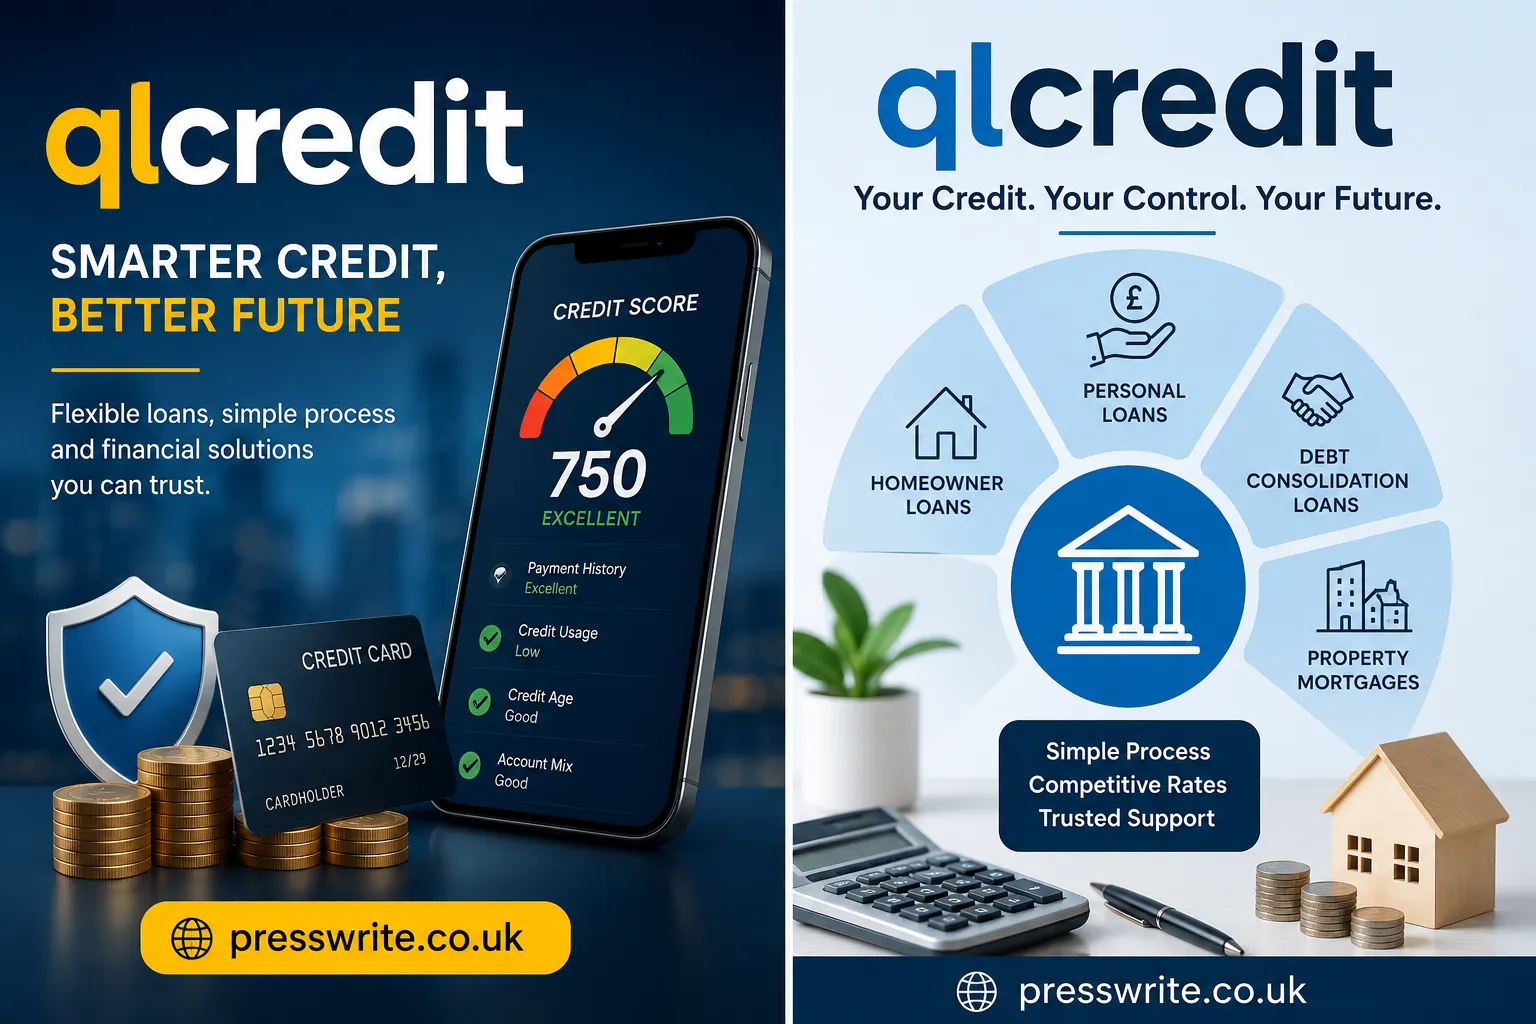
When people search for qlcredit, they may be looking for information about a lending company, personal financing, property-related borrowing, or the wider idea of digital credit. The term can therefore create some confusion, especially because several websites describe it in different ways.
For a reliable understanding, it is important to separate general descriptions from information that can be verified through primary sources. In the financial context, QLCredit is closely associated with QL Credit Gain Finance Company Limited, a Hong Kong-based licensed money lender operating under the Credit Gain business. The company’s own website identifies QL Credit Gain Finance Company Limited and provides information about personal loans, debt consolidation loans, homeowner loans, and property mortgages.
This guide explains what qlcredit means, how its lending services work, what borrowers should check before applying, and why responsible borrowing matters. It is designed for beginners as well as readers who want a clearer understanding of the company and the broader credit process.
What Is qlcredit?
The first step in understanding qlcredit is identifying what the term refers to.
In the lending context, qlcredit is associated with QL Credit Gain Finance Company Limited, also known in Chinese as 乾隆領達財務有限公司. According to the company’s official website, QL Credit Gain Finance Company Limited operates alongside KP Credit Gain Finance Company Limited, with both companies described as wholly owned subsidiaries of China Financial Services Holdings Limited.
The company’s website lists several financing categories, including:
- Personal loans
- Debt consolidation loans
- Homeowner loans
- Property mortgages
This distinction is important because qlcredit should not automatically be treated as the name of a universal credit score, credit bureau, or government financial program. A lender provides financing, evaluates applications, and manages repayment, while a credit reference agency has a different role.
For someone searching for qlcredit online, checking the exact company name, licensing information, website domain, and loan documentation is therefore more useful than relying on vague descriptions.
Who Operates QLCredit?
Understanding ownership and corporate identity is an important part of financial due diligence.
The official Credit Gain website states that QL Credit Gain Finance Company Limited and KP Credit Gain Finance Company Limited are wholly owned subsidiaries of China Financial Services Holdings Limited, a Hong Kong-listed company. The same source says that the Credit Gain business focuses on personal and property lending in Hong Kong.
The company identifies QL Credit Gain Finance Company Limited with Money Lender’s Licence No. 1988/2025 on its website.
The Hong Kong Companies Registry also maintains an official system for checking licensed money lenders. Its guidance explains that members of the public can search the list of existing licensed money lenders and use the electronic search service to inspect relevant records.
That provides an important lesson for anyone researching an online lender: do not judge a financial service only by its website design, advertisements, or search-engine rankings. Verify the legal entity and licensing position through an appropriate official source.
What Financial Services Does QLCredit Offer?
The services associated with qlcredit are primarily related to borrowing and property finance.
The official Credit Gain website presents four main categories of loan applications:
| Loan type | General purpose | What borrowers should examine |
| Personal loan | Personal financial needs | Interest, fees, repayment amount |
| Debt consolidation loan | Combining existing debts | Total cost after consolidation |
| Homeowner loan | Financing based on home ownership | Security and property-related obligations |
| Property mortgage | Property financing | Interest, term, collateral and repayment |
These categories can serve different financial needs, but the existence of a particular loan category does not mean that every applicant will qualify for it.
Loan approval normally depends on the lender’s assessment of the applicant and the information provided during the application process. The company’s online application statement says that applicants authorize credit checks and verification of information with credit reference agencies.
For that reason, borrowers should provide accurate information and understand that submitting an application is not the same as receiving guaranteed approval.
How Does the QLCredit Application Process Work?
The exact approval process can depend on the type of financing requested and the applicant’s circumstances. However, the available official information provides a useful picture of the basic process.
A typical borrowing journey may involve the following stages:
- Selecting a loan category: The applicant identifies whether the requirement is a personal loan, debt consolidation, homeowner loan, or property mortgage.
- Providing application information: Basic personal and financial information is submitted.
- Verification: Information may be checked for accuracy.
- Credit assessment: The lender may obtain information from credit reference agencies.
- Review of terms: If financing is offered, the borrower should review the amount, interest rate, repayment period, fees, and other conditions.
- Agreement and repayment: Once the borrower accepts the relevant terms and completes the required documentation, the facility proceeds according to the agreement.
The official online application statement specifically notes that the company may conduct credit checks and verify information supplied by customers.
This makes accuracy especially important. A borrower should never exaggerate income, hide relevant liabilities, or provide false personal information simply to improve the apparent chances of approval.
Understanding Interest Rates and Repayment Costs
One of the most important parts of researching qlcredit—or any lender—is understanding the total cost of borrowing.
The official Credit Gain website states that, under the Money Lenders Ordinance, the annual interest rate cannot exceed 48%, and gives an illustrative example involving a HK$10,000 loan at an annual rate of 30% over 12 installments. The example states a monthly repayment of HK$975 and a total repayment of HK$11,700.
This example should be treated as an illustration rather than a promise of the rate or repayment terms that any individual applicant will receive.
Before accepting financing, a borrower should look beyond the headline interest rate and ask:
- What is the annual interest rate?
- Is the rate fixed or variable?
- What is the total repayment amount?
- How many installments are required?
- Are there arrangement or administrative fees?
- Are there late-payment consequences?
- Is collateral required?
- What happens if the loan is repaid early?
- Are there additional costs connected with a secured loan?
A loan with a lower monthly installment is not automatically cheaper. Extending the repayment period can sometimes reduce the monthly burden while increasing the total amount paid over the life of the loan.
Is QLCredit Licensed and Legitimate?
This is one of the most important questions people ask when searching for qlcredit.
The official company website identifies QL Credit Gain Finance Company Limited as a money lender and lists Money Lender’s Licence No. 1988/2025.
The Hong Kong Companies Registry provides an official mechanism for checking licensed money lenders. It explains that people can search the list of existing money lenders and inspect relevant registered information through its services.
The Registry’s published licensee list has also identified QL Credit Gain Finance Company Limited among Hong Kong money lenders.
However, licensed does not mean every loan is suitable for every borrower. Regulation and licensing are important indicators of legal status, but borrowers still need to assess affordability, interest costs, security requirements, contractual obligations, and the consequences of missed payments.
This is where E-E-A-T matters: trustworthy financial content should distinguish between evidence of licensing and a personal recommendation to borrow.
What Should Borrowers Check Before Applying?
A careful borrower should never rush into a loan simply because funds appear to be available quickly.
Before applying for qlcredit or any other lender, create a simple checklist.
Verify the Company
Check the exact legal name of the lender and compare it with official licensing information. Hong Kong’s Companies Registry specifically recommends using its licensed-money-lender search resources to verify licensing status.
Review the Full Cost
Do not focus only on the advertised interest rate. Calculate the expected total repayment and identify additional fees.
Check Affordability
Ask whether the monthly payment remains manageable after rent, household expenses, existing debt, savings, and unexpected costs are considered.
Understand Security
If the financing is secured against property or another asset, understand exactly what is being pledged and what could happen if repayments are not made.
Read the Agreement
Never rely solely on an advertisement or verbal explanation. The written agreement should be reviewed before accepting the facility.
These checks can turn a rushed borrowing decision into a more informed financial decision.
QLCredit and Debt Consolidation
Debt consolidation is another area where borrowers need to think beyond convenience.
The official Credit Gain website lists debt consolidation as one of its loan categories.
Debt consolidation generally involves using a new financing facility to manage or repay multiple existing debts. The potential attraction is simplicity: instead of handling several repayment schedules, a borrower may have a more centralized repayment arrangement.
But consolidation does not automatically eliminate debt.
Before choosing this type of financing, compare:
| Question | Why it matters |
| What debts will be consolidated? | Shows the actual amount being replaced |
| What is the new interest rate? | Determines borrowing cost |
| What is the new repayment period? | A longer term can increase total interest |
| Are there additional fees? | Fees can reduce the financial benefit |
| What will the monthly payment be? | Helps assess affordability |
| Will existing credit accounts remain open? | Prevents creating new debt after consolidation |
The key question is not simply, “Will my monthly payment become smaller?” A better question is, “Will this arrangement improve my overall financial position after considering the complete cost?”
QLCredit for Property and Homeowners
Property-related finance can involve considerably larger amounts and therefore deserves additional caution.
QLCredit’s official website lists both homeowner loans and property mortgages among its available financing categories.
Secured borrowing can provide access to larger financing amounts because an asset may be used as security. However, this also means that the consequences of default can be more serious than with some forms of unsecured borrowing.
Potential borrowers should carefully consider:
- The property’s current value
- The amount being borrowed
- The interest rate
- The repayment period
- Existing mortgages or charges
- Legal and administrative expenses
- Early repayment conditions
- Default consequences
- Whether the household can continue repayments if income changes
Property should never be used as security without understanding the contractual consequences.
For large loans, independent professional advice may also be appropriate, particularly when the financing involves significant assets or complex legal arrangements.
How to Recognize Red Flags Around Online Credit
Searching for qlcredit can lead users to official websites, review pages, advertisements, social posts, and unrelated services. This makes online verification especially important.
Be cautious when you encounter:
- Requests for payment before a loan is properly documented
- Pressure to make an immediate decision
- Unusually attractive promises with no clear conditions
- Requests to send sensitive information through unofficial channels
- Websites that imitate a legitimate lender
- Contact details that do not match the official company’s information
- Claims of guaranteed approval
- Requests to pay an intermediary instead of dealing with the lender
- Loan terms that are difficult to understand or unexpectedly change
The safest approach is to verify the lender independently rather than clicking a promotional link and assuming that everything is genuine.
The Hong Kong Companies Registry explicitly provides public resources for checking whether a company is a licensed money lender.
How to Use Credit Responsibly
Responsible borrowing begins before the application.
A borrower should first identify the reason for borrowing and determine whether credit is genuinely necessary. A loan can solve a short-term liquidity problem, finance a property-related need, or reorganize existing debt, but borrowing also creates a future obligation.
A practical approach is to:
- Define the exact amount required.
- Avoid borrowing more than necessary.
- Compare the complete cost of available options.
- Calculate the monthly repayment.
- Leave room in the budget for emergencies.
- Read all contractual conditions.
- Keep copies of loan documents.
- Make payments on time.
- Contact the lender promptly if financial difficulty develops.
Good credit management is less about finding the fastest loan and more about choosing an obligation that remains manageable over time.
QLCredit vs. a Credit Score or Credit Bureau
One common source of confusion is treating the name qlcredit as though it were automatically a consumer credit score.
These concepts are different.
A lender provides financing.
A credit reference agency or bureau maintains or provides credit information according to its applicable rules.
A credit score is a numerical assessment that may be calculated using information from a person’s credit history and other permitted factors.
QL Credit Gain Finance Company Limited is presented by its official website as a lender, not as a universal credit-score provider. Its application statement instead says that it may obtain credit information from credit reference agencies when carrying out credit checks.
This distinction is useful when searching online because it helps users avoid confusing the company with unrelated credit-scoring products or websites using similar terminology.
Frequently Asked Questions About QLCredit
What is qlcredit?
In the financial context, qlcredit is associated with QL Credit Gain Finance Company Limited, a Hong Kong money lender offering financing categories such as personal loans, debt consolidation loans, homeowner loans, and property mortgages.
Is QLCredit a bank?
QL Credit Gain Finance Company Limited is presented as a finance company and licensed money lender rather than a conventional bank. The official company information identifies it as a money-lending business.
Is QLCredit licensed?
The company’s official website lists QL Credit Gain Finance Company Limited with Money Lender’s Licence No. 1988/2025. Hong Kong’s Companies Registry also provides an official licensed-money-lender search facility for verification.
What types of loans are associated with QLCredit?
The official website lists personal loans, debt consolidation loans, homeowner loans, and property mortgages.
Does QLCredit guarantee loan approval?
Borrowers should not assume that approval is guaranteed. The application process includes information verification and credit assessment, and eligibility depends on the lender’s evaluation.
Can QLCredit check credit information?
Yes. The company’s online application statement says that it may contact relevant parties and obtain credit information from credit reference agencies for credit checking and verification.
What interest rate does QLCredit charge?
The official website states that, under the Money Lenders Ordinance, the annual interest rate cannot exceed 48%, while individual loan terms can vary. It also publishes an illustrative repayment example at a 30% annual rate.
Is a QLCredit loan right for everyone?
No financial product is automatically suitable for everyone. A borrower should compare the complete cost, repayment obligations, security requirements, and personal affordability before making a decision.
Final Perspective on QLCredit
Understanding qlcredit requires more than reading a short description or trusting the first search result. The most useful approach is to establish the identity of the lender, verify licensing information, understand the available financing categories, and carefully evaluate the cost and risks of borrowing.
Current primary-source information identifies QL Credit Gain Finance Company Limited as a Hong Kong money lender with a listed licence number, while the company’s website describes personal, debt-consolidation, homeowner, and property-mortgage financing.
For consumers, the bigger lesson goes beyond one company: financial convenience should never replace financial due diligence. Before signing any credit agreement, verify who you are dealing with, calculate what you will repay, understand what happens if circumstances change, and make sure the borrowing decision fits your wider financial situation.
The strongest financial decision is not necessarily the one that provides money fastest. It is the one made with clear information, realistic affordability, and a full understanding of the obligation that comes afterward.